

Documents You Need to Receive Money From Abroad in Vietnam

Two things are mandatory in every case. The recipient needs a valid identity document, meaning a chip-enabled citizen identity card or a passport, and if the funds are going to a bank account, that account must have completed biometric verification. Everything else depends on the collection channel and the purpose of the funds.
There is a third requirement that sits with the sender rather than the recipient, and it causes more delays than any document: the beneficiary name on the transfer instruction has to match the recipient's identity document exactly.
This article sets out the full document list by channel, explains which regulation sits behind each requirement, and lists the seven most common causes of delay. If you are sending money to family in Vietnam, the first two sections are the ones to forward to them.
Quick reference: documents by collection channel
Requirements differ depending on how the recipient collects the funds.

One condition applies to all four channels without exception: the beneficiary details on the transfer instruction must match the recipient's identity document exactly.
Getting the beneficiary name exactly right
This is the section for senders, and it is the highest-value thing you can get right before pressing send.
Vietnamese names create three specific failure modes for people entering them from abroad:
- Diacritics. A Vietnamese identity document shows the name with diacritical marks, for example, Nguyễn Văn Thành. International transfer systems generally cannot carry those marks, so the name travels as NGUYEN VAN THANH. That is expected and correct. The problem arises when a sender substitutes or drops letters rather than simply removing the marks, for example, writing Nguyen Van Thanh as Nguyen Van Than.
- Name order. Vietnamese names are written with the surname first, then the middle name, then the given name. Systems that assume a Western first name and last name order can reverse them. Enter the name in the same order as it appears on the identity document, from left to right.
- Missing middle names. Middle names are part of the legal name in Vietnam and are not optional. Dropping Van or Thi from a name is enough to create a mismatch.
The practical fix takes one minute. Ask the recipient to send you a photograph of the information page of their identity document or passport, and type the name exactly as printed, without diacritics, in the same order. Do not work from memory or from how the name is spelled in messaging apps.
The same discipline applies to the account number, the bank name, and the SWIFT or bank code. An error in any of these usually results in the transfer being returned, which costs both time and additional charges.
Identity documents: what changed
Several English-language guides on this topic are out of date, including at least one updated in 2026 that still lists the old identity card as acceptable.
Under the Identification Law 2023, the old Vietnamese identity card known as CMND, in both its 9-digit and 12-digit versions, ceased to be valid for procedures and transactions after 31 December 2024. From 1 January 2025, Vietnamese banks began suspending transactions on accounts still registered against that document.
Documents currently accepted:
- A citizen identity card or chip-enabled citizen identity card that remains valid, for Vietnamese nationals.
- A valid passport.
- For foreign nationals: a passport together with valid evidence of permitted residence, such as a visa, a temporary residence card, or a permanent residence card.
One detail is easy to miss. Holding a valid document is not sufficient on its own. The details must also be correctly recorded in the systems of the bank or disbursing institution. Many people have replaced their identity card without notifying their bank, which continues to hold the superseded number.
Biometric verification: the step that blocks access to funds
This is the most important point in the article, and guidance on receiving money rarely mentions it.
Article 17, clause 5(c) of Circular 17/2024/TT-NHNN provides that an account holder may only withdraw funds and carry out payment transactions by electronic means after identity document details and biometric information have been matched successfully. The biometric data must correspond either to the data stored in the chip of a citizen identity card issued by the police authority or be verified through the holder's electronic identification account.
The practical consequence is specific: funds can arrive in the account and still be unusable through electronic channels until verification is complete. The money is not lost, but it sits there.
Circular 25/2025/TT-NHNN introduced a limited set of exclusions from this requirement. If your circumstances are unusual, ask your bank what applies in your case.
Verification can usually be completed through the bank's mobile application, provided the phone has NFC to read the card chip, or in person at a branch. Complete it before the transfer is sent rather than dealing with it afterwards.
Supporting documents by purpose and what to keep
Beyond identity documents, the disbursing institution may ask for evidence clarifying the nature of the funds. What is requested depends on the purpose.
- Funds sent by a relative. Prepare evidence of the family relationship, such as a birth certificate, marriage certificate, or equivalent. Also useful is evidence of the sender's status abroad: passport, residence card, foreign employment contract, or enrollment confirmation.
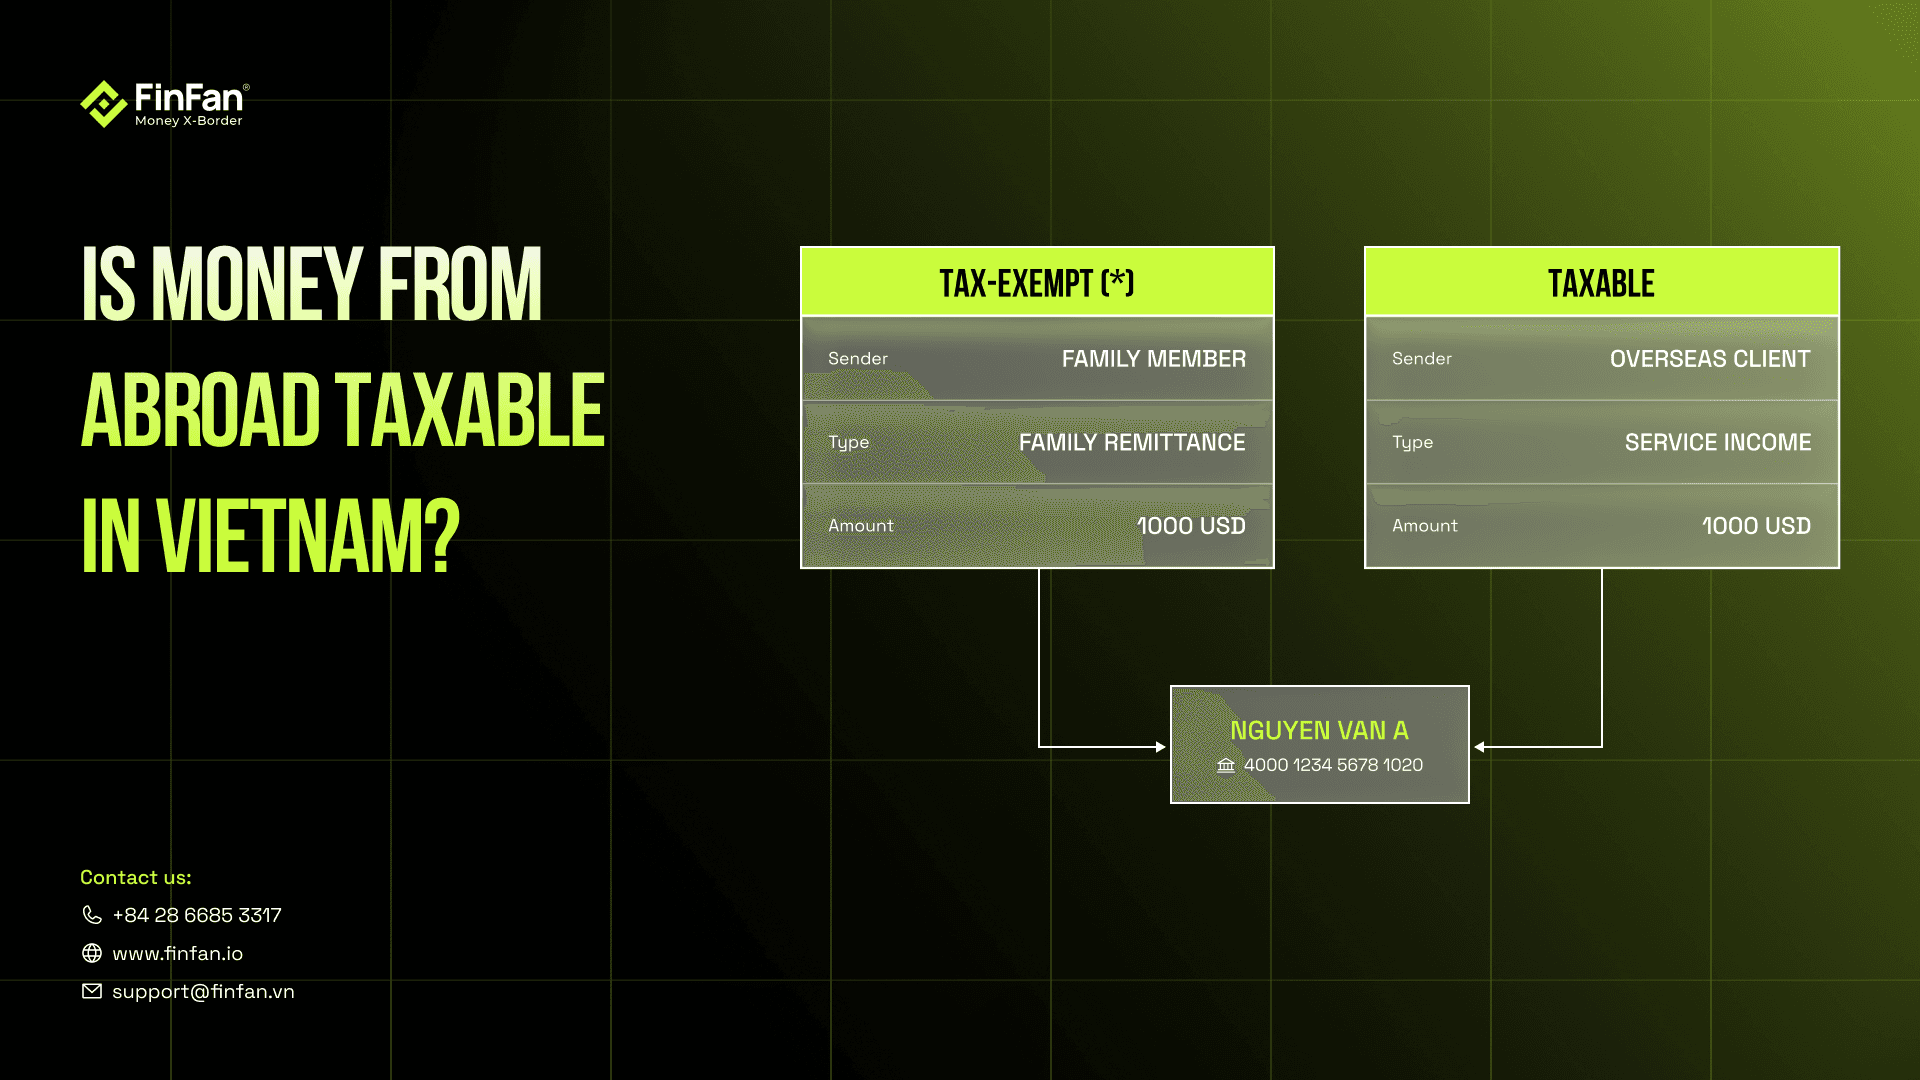
- Payment for goods or services. Prepare the contract, invoice, order, or equivalent documentation showing that a genuine transaction took place. This category is taxable income, so the file serves two purposes at once.
- Loans, repayments, and other support. Documentation of the arrangement between the parties, where it exists.
A point that applies throughout: the transfer reference should state the purpose clearly at the moment the sender creates the instruction. A blank or vague reference is a common reason a transfer is paused for enquiry. Asking the sender to state the purpose properly the first time saves days later.
Records to keep for tax purposes. The document set used to collect funds and the set used for tax are not identical, so keep both. Article 25, clause 3 of Decree 253/2026/ND-CP establishes that the basis for demonstrating exempt remittance income is the evidence of the source of funds received from abroad, together with the disbursing organization's payment records where applicable. In practice, retain four items: the transaction record, the transfer reference stating the purpose, proof of the family relationship, and proof of the sender's status abroad. Keep digital copies filed by year.
Why you get asked for more information
Many recipients become anxious when asked for documents, assuming something is wrong with their transfer. In most cases, this is a legal obligation of the financial institution rather than a sign of a problem.
Under Article 9 of Circular 27/2025/TT-NHNN, in force since 1 November 2025, financial institutions must collect information and report to the Anti-Money Laundering Department in respect of:
- International electronic funds transfers of US$1,000 or more, or the equivalent in another currency.
- Domestic electronic funds transfers of VND 500 million or more.
The US$1,000 threshold is worth noting because it equates to roughly VND 26 million. Most family transfers into Vietnam exceed it, which means being within the reporting scope is the norm rather than the exception.
Separately, the large-value transaction reporting threshold is VND 400 million or more under Decision 11/2023/QD-TTg. That threshold also triggers customer due diligence obligations in certain circumstances.
The distinction that matters to you: the reporting obligation sits with the financial institution, not with you. You do not file anything. Your part is simply to provide accurate information when asked.
Foreign residents, organizations, and third-party collection
Foreign nationals resident in Vietnam. In addition to a passport, you need valid evidence of permitted residence. Banks are required to record and monitor this, and will suspend transactions when the residence document expires. This is the single most common account problem for long-term foreign residents, and it is entirely avoidable: renew and notify your bank before the expiry date, not after.
Organizations receiving funds. Under Circular 17/2024/TT-NHNN, the bank must collect and monitor the identity documents of the legal representative, together with that person's biometric information, where transactions are carried out electronically. If the representative has not completed verification, the organization's account is restricted for electronic transactions in the same way an individual account would be.
Collecting on behalf of someone else. A valid authorization document is required, along with identity documents for both parties. Third-party collection typically triggers additional verification, so where it is practical, have the named beneficiary collect the funds directly.
Addresses after administrative reorganization. Following the reorganization of administrative units from 2025, many place names have changed. If the address on your identity document differs from the address held by your bank, update it in advance to avoid a mismatch during verification.
Seven common causes of delay
Drawing on disbursement practice, most friction falls into seven categories. The first four sit in the transfer instruction and are the sender's to get right. The last three sit in the recipient's records with their bank in Vietnam. All seven are preventable.
Four in the transfer instruction
1. The beneficiary name does not match the identity document.
A missing middle name, altered spelling, or reversed name order. Matching is exact, so NGUYEN THI MAI ANH and NGUYEN MAI ANH are treated as two different people. The three failure modes specific to Vietnamese names, and how to avoid them, are set out in the section on getting the beneficiary name right above.
2. Incorrect beneficiary bank details.
A wrong account number, bank code or SWIFT code. The consequence is more serious than the others: the funds are generally returned to the sending end rather than held for enquiry, so the sender has to start again and may pay a second charge. Send these details in writing so they can be copied rather than retyped.
3. Incomplete sender information.
The sender's name, address, and country must appear in full on the instruction. For larger amounts, thin sender details oblige the disbursing institution to go back to the sending end for more, and this is usually the longest wait of the seven because it depends on time zones and on how quickly the other side replies. Ask the sender to complete every field from the first transfer, the residential address in particular.
4. A blank or vague transfer reference, or a purpose that does not match at both ends.
A reference such as "transfer" or an empty field triggers an inquiry into the purpose. The less obvious half of this: when collecting cash at a counter, the recipient is asked what the funds are for, and that answer has to match what the sender wrote on the instruction. A mismatch—the sender stating family support while the recipient says payment for goods—obliges the disbursing institution to stop and clarify, because the two purposes carry entirely different documentation requirements. Agree on the purpose in advance and state the same thing at both ends. Replaced, but the bank still holds the old number.
Three in the recipient's records
1. An identity document no longer valid for use.
For Vietnamese nationals, usually the superseded CMND card. For foreign nationals, usually an expired visa or residence card. Banks are required to monitor these expiry dates and will suspend transactions once a document lapses, even where the account continues to work normally for domestic transactions.
2. Document details not updated with the bank.
The quietest of the seven. The card has been replaced, the document is entirely valid, but the bank's system still holds the superseded number because it was never notified. During matching, the system sees a document number that is no longer valid and stops the transaction. Replacing the document with the authorities and updating it with the bank are two separate steps.
3. Biometric verification not completed.
Unlike the other six, this one does not stop the funds arriving. They credit normally but cannot be withdrawn or forwarded electronically until matching is complete, which most people discover only when a transfer attempt is declined. A number of exclusions apply to this requirement, so anyone in an unusual situation should ask their bank what applies to them.
Frequently asked questions
Do I need to bring documents if the money goes to my bank account?
If the funds are credited directly to your account, no counter visit is needed. The conditions are that your account has completed biometric verification and that your identity document details are current in the bank's records. You would only need to provide further documentation if the disbursing institution requests additional verification.
Is the old Vietnamese identity card still accepted?
No. Under the Identification Law 2023, the CMND card in both its 9-digit and 12-digit versions ceased to be valid for procedures and transactions after 31 December 2024. You need a citizen identity card or a passport, and you should update the details with your bank.
Why has my transfer been held for additional documents?
The most common reasons are that the transaction value exceeded a threshold triggering the institution's information collection obligations under anti-money laundering rules or that the details on the transfer instruction were incomplete or unclear. This is routine verification and not an indication that anything is wrong.
What does the sender need to prepare abroad?
Accurate beneficiary details: the full name exactly as printed on the identity document, the account number, and the beneficiary bank name and code. The transfer reference should state the purpose. The sending institution in your country may also require its own documentation under local rules.
What is needed to collect cash at a counter?
An original valid identity document and the transaction reference provided by the sender, or a collection notice where the disbursing institution issues one. It is worth bringing the sender's details as well, in case they are needed for verification.
In summary
Preparing to receive money from abroad in Vietnam comes down to three things: a valid identity document that is correctly recorded with your bank, an account that has completed biometric verification, and beneficiary details that match your identity document exactly. Those three cover almost every problem that arises.
A practical next step. If you are the recipient, check whether the identity document registered with your bank is still valid and whether biometric verification is complete. If you are the sender, ask for a photograph of the recipient's identity document page and enter the name exactly as printed before your first transfer.
For less common situations, such as third-party collection, receipt by an organisation, or funds with a specific declared purpose, contact the bank or disbursing institution directly for guidance on your case.
References
- Law on Identification 2023 (Law No. 26/2023/QH15)
- Circular 27/2025/TT-NHNN guiding the implementation of the Law on Anti-Money Laundering, effective 1 November 2025
- Decision 11/2023/QĐ-TTg on the threshold for high-value transactions subject to reporting
- Decree 253/2026/NĐ-CP detailing the implementation of the Law on Personal Income Tax
- Consolidated Document 21/VBHN-NHNN dated 18 September 2025, consolidating the Circular on opening and using payment accounts at payment service providers
Disclaimer
FinFan is a brand of Nhat Phuong Joint Stock Company (Best Way Corporation), operating under License No. 973/GP-HCM for Foreign Currencies Acceptance and Payment issued by the State Bank of Vietnam. FinFan provides infrastructure and disbursement services for inbound foreign currency flows into Vietnam on behalf of international money transfer operators, banks, and partners.
FinFan is not a bank, does not accept deposits, and does not provide outbound money transfer services from Vietnam. This content is provided for information only. Documentation requirements vary between institutions and over time; readers should confirm the applicable requirements with their own bank or disbursing institution.
This content is provided for information only and does not constitute legal or tax advice. Regulations and documentation requirements change over time and vary between institutions. For a specific situation, confirm the position with your bank, your disbursing institution or the tax authority.

Dr. Tuyen Nguyen
Money Beyond Borders